2026 Capital Gains Tax Reforms: Optimize Your Returns Now
Anúncios
Demystifying 2026 Capital Gains Tax Reforms: Strategies to Optimize Your Returns
The financial landscape is ever-evolving, and staying ahead of impending changes is crucial for astute investors. As we approach 2026, significant discussions and potential legislative actions surrounding capital gains tax reforms are gaining momentum. Understanding these potential shifts is not just about compliance; it’s about strategically positioning your investments to optimize returns and minimize liabilities. This comprehensive guide will demystify the anticipated 2026 capital gains tax reforms, explore their potential impact, and provide actionable strategies to safeguard and grow your wealth.
Anúncios
For many investors, capital gains tax represents a substantial portion of their tax burden. Any alteration to these regulations can have far-reaching effects on investment decisions, portfolio structuring, and overall financial planning. Proactive engagement with these potential changes is key to transforming what could be a challenge into an opportunity for enhanced financial health.
Understanding Capital Gains Tax: The Basics Before 2026
Before diving into the specifics of potential 2026 capital gains reforms, it’s essential to have a solid understanding of how capital gains are currently taxed. Capital gains are profits you make from selling an asset that has increased in value, such as stocks, bonds, real estate, or collectibles. These gains are typically categorized into two types:
Anúncios
- Short-Term Capital Gains: These are profits from assets held for one year or less. They are taxed at your ordinary income tax rates, which can be as high as 37% for the top federal bracket.
- Long-Term Capital Gains: These are profits from assets held for more than one year. They are generally taxed at more favorable rates: 0%, 15%, or 20%, depending on your taxable income.
The distinction between short-term and long-term gains is paramount, as it significantly impacts your tax liability. This foundational knowledge will help you better appreciate the implications of any upcoming changes to the tax code.
The Current Tax Landscape: A Brief Overview
Currently, the long-term capital gains tax rates are structured as follows for 2024 (these figures are subject to annual adjustments for inflation):
- 0% Rate: For individuals with taxable income up to $47,025 (single filers) or $94,050 (married filing jointly).
- 15% Rate: For individuals with taxable income between $47,026 and $518,900 (single filers) or $94,051 and $583,750 (married filing jointly).
- 20% Rate: For individuals with taxable income exceeding $518,900 (single filers) or $583,750 (married filing jointly).
It’s also important to remember the Net Investment Income Tax (NIIT) of 3.8%, which applies to certain net investment income for individuals with modified adjusted gross income (MAGI) above specific thresholds ($200,000 for single filers, $250,000 for married filing jointly). This tax can effectively increase your capital gains tax rate.
What to Expect: Potential 2026 Capital Gains Tax Reforms
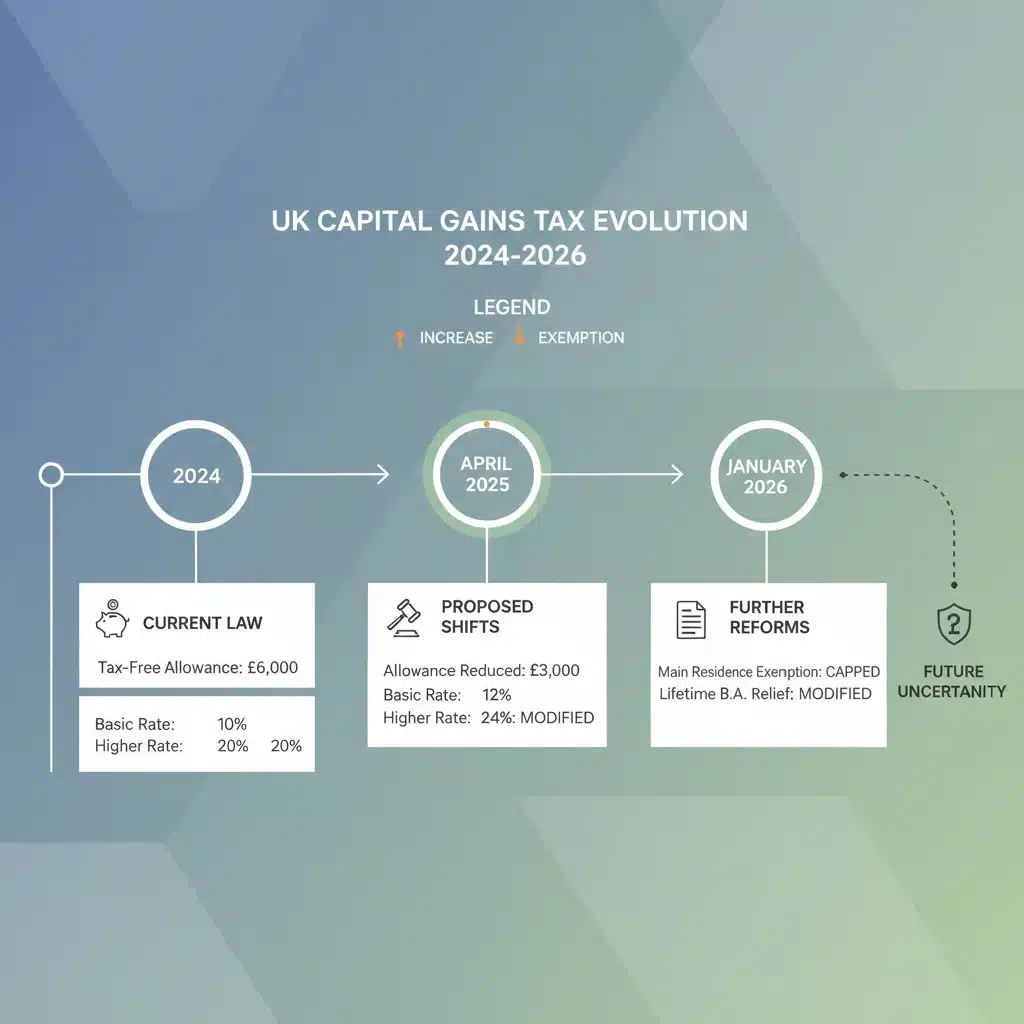
While the exact nature of the 2026 capital gains tax reforms remains subject to legislative debate and political outcomes, several key areas are frequently discussed and could significantly alter the current tax framework. These discussions often revolve around:
1. Changes to Long-Term Capital Gains Rates
One of the most widely discussed proposals involves increasing the long-term capital gains tax rates, potentially aligning them more closely with ordinary income tax rates for high-income earners. This could mean the elimination or reduction of the preferential 0%, 15%, and 20% rates, leading to a substantial increase in tax liability for investors. For instance, proposals have suggested taxing capital gains at ordinary income rates for those earning over a certain threshold, such as $1 million annually.
2. Adjustments to the Holding Period
Another potential reform could involve extending the holding period required to qualify for long-term capital gains treatment. Currently, an asset must be held for more than one year. A change could see this extended to two, three, or even five years, which would impact trading strategies and investment horizons, particularly for those who frequently rebalance their portfolios or invest in faster-moving assets.
3. Modifications to Step-Up in Basis Rules
The step-up in basis rule is a significant benefit for heirs, as it resets the cost basis of inherited assets to their market value on the date of the original owner’s death. This effectively eliminates capital gains tax on appreciation that occurred during the deceased’s lifetime. Proposals have been floated to eliminate or significantly modify this rule, which would have profound implications for estate planning and wealth transfer.
4. Wealth Taxes and Mark-to-Market Taxation
While more radical, discussions around wealth taxes or mark-to-market taxation for certain assets have also surfaced. A wealth tax would tax assets annually regardless of whether they are sold, while mark-to-market taxation would require investors to pay taxes on unrealized gains of certain assets each year. These concepts are generally more complex to implement and have faced considerable opposition, but they remain part of the broader tax reform conversation.
5. Changes to Qualified Business Income (QBI) Deduction
Although not directly a capital gains tax, the Qualified Business Income (QBI) deduction (Section 199A) is set to expire at the end of 2025. This deduction allows eligible self-employed and small business owners to deduct up to 20% of their qualified business income. Its expiration or modification in conjunction with other tax changes could indirectly affect how business owners manage their investments and capital gains.
Impact Analysis: How 2026 Capital Gains Reforms Could Affect You
The potential 2026 capital gains tax reforms could have a varied impact depending on your income level, investment portfolio, and financial goals. It’s crucial to assess how these changes might specifically affect your situation.
High-Net-Worth Individuals and Investors
High-net-worth individuals (HNWIs) are likely to feel the most significant impact, especially if long-term capital gains rates are increased or aligned with ordinary income rates. This could lead to a substantial reduction in after-tax returns on their investment portfolios. The elimination of the step-up in basis rule would also significantly affect estate planning for wealthy families, potentially leading to higher tax burdens for heirs.
Middle-Class Investors
Middle-class investors might see less direct impact if reforms primarily target high-income earners. However, changes to holding periods could affect their investment strategies, particularly for those who manage their own portfolios and engage in more active trading. The overall market sentiment and economic impact of tax changes could also indirectly affect their investments.
Real Estate Investors
Real estate investors could be particularly affected by changes to capital gains taxes, especially if they frequently buy and sell properties. The 1031 exchange (like-kind exchange) allows investors to defer capital gains taxes when reinvesting proceeds from a property sale into a similar property. While not directly a capital gains rate change, any broader tax reform could potentially review or modify such deferral mechanisms, adding another layer of complexity.
Retirement Planning
For those nearing or in retirement, capital gains tax changes can significantly alter withdrawal strategies and the longevity of their portfolios. Higher taxes on asset sales might necessitate a re-evaluation of income sources and spending plans. Understanding the implications for your retirement nest egg is paramount.
Proactive Strategies to Optimize Your Returns Before 2026
Given the potential for significant changes, now is the time to review your financial plan and implement strategies to mitigate potential negative impacts and optimize your returns under the new tax regime. Here are several proactive steps to consider:
1. Tax-Loss Harvesting
Tax-loss harvesting is a strategy where you sell investments at a loss to offset capital gains and, potentially, a limited amount of ordinary income ($3,000 per year). This strategy is most effective when you have significant capital gains. By realizing losses now, you can reduce your current tax liability and potentially carry forward any excess losses to future years. This can be particularly beneficial if capital gains rates are expected to rise.
2. Rebalancing Your Portfolio and Realizing Gains Strategically
Consider rebalancing your portfolio to align with your long-term goals and risk tolerance. If you have highly appreciated assets that you plan to sell in the near future, consider realizing those gains before potential tax increases in 2026. This requires careful planning, as accelerating gains might trigger a higher tax bill in the current year, but it could be lower than what you’d face post-reform.
3. Utilizing Tax-Advantaged Accounts
Maximize contributions to tax-advantaged retirement accounts like 401(k)s, IRAs, Roth IRAs, and HSAs. Investments within these accounts grow tax-deferred or tax-free, shielding them from capital gains taxes until withdrawal (or entirely in the case of Roth accounts). This strategy becomes even more valuable if capital gains rates increase.
4. Gifting Strategies
If you are considering gifting assets to family members, doing so before potential changes to the step-up in basis rule could be advantageous. Gifting appreciated assets to individuals in lower tax brackets might also enable them to sell the assets and pay less in capital gains tax, although this depends on various factors including the donee’s income and the gift tax exclusion limits.
5. Consider Qualified Opportunity Funds (QOFs)
Qualified Opportunity Funds allow investors to defer and potentially reduce capital gains taxes by reinvesting those gains into designated low-income communities. While these investments come with their own risks and complexities, they can be a powerful tool for tax deferral and elimination, especially if held for the long term (10+ years).
6. Reviewing Your Estate Plan
If the step-up in basis rule is modified or eliminated, your estate plan will need a significant overhaul. Consult with an estate planning attorney to explore strategies such as trusts, life insurance, or other wealth transfer mechanisms that can help mitigate future tax burdens on your heirs.
7. Diversification and Long-Term Investing
While not directly a tax strategy, maintaining a well-diversified portfolio and focusing on long-term investing principles can help weather market volatility and tax changes. Less frequent trading generally leads to fewer realized capital gains, and a diversified portfolio can offer resilience against specific asset class fluctuations.
8. Consulting with Financial and Tax Professionals
The most crucial step is to consult with a qualified financial advisor and tax professional. They can provide personalized advice based on your unique financial situation, risk tolerance, and goals. They can help you understand the nuances of potential reforms and craft a strategy that aligns with your overall financial objectives.
The Broader Economic and Market Implications
Beyond individual investor strategies, the 2026 capital gains tax reforms could have broader economic and market implications. Higher capital gains taxes might:
- Impact Investment Behavior: Investors might hold onto assets longer to defer taxes, or shift investments towards tax-advantaged vehicles.
- Affect Venture Capital and Startups: Higher taxes on exit events could reduce the incentive for venture capital investments, potentially impacting innovation and economic growth.
- Influence Market Volatility: Anticipation of tax changes can lead to increased market activity as investors adjust their portfolios, potentially causing short-term volatility.
- Alter Capital Formation: Changes could affect the availability of capital for businesses and new ventures, depending on how investors react to altered after-tax returns.
It’s important to monitor these broader trends as they can indirectly influence your investment performance and strategic decisions.
Staying Informed: Your Best Defense
The legislative process is often dynamic and unpredictable. What is proposed today might be significantly altered tomorrow. Therefore, staying informed is paramount. Follow reputable financial news sources, subscribe to updates from financial institutions, and maintain open communication with your financial and tax advisors.
Key dates to watch include:
- Mid-term elections: Political shifts can significantly influence the direction and likelihood of tax reforms.
- Congressional legislative sessions: Pay attention to bills introduced and debated in Congress.
- Economic reports: Broader economic conditions can sometimes dictate the urgency or nature of tax policy changes.
Conclusion: Navigating the Future of Capital Gains
The potential 2026 capital gains tax reforms represent a significant inflection point for investors. While the exact contours of these changes are yet to be fully defined, the prudent investor will use this period of anticipation to review, plan, and adapt. By understanding the potential shifts, analyzing their personal impact, and implementing proactive strategies such as tax-loss harvesting, utilizing tax-advantaged accounts, and strategic gifting, you can position yourself to not only mitigate potential downsides but also optimize your returns in the evolving tax landscape.
Remember, financial planning is an ongoing process. Regular reviews of your portfolio and tax strategy, coupled with expert advice, will ensure that your financial goals remain on track, no matter what changes the future brings. Don’t wait until the last minute; start preparing for 2026 today.