Navigating 3.5% Inflation: Investment Portfolio Adjustments for 2026
Anúncios
Navigating 3.5% Inflation: Investment Portfolio Adjustments for 2026
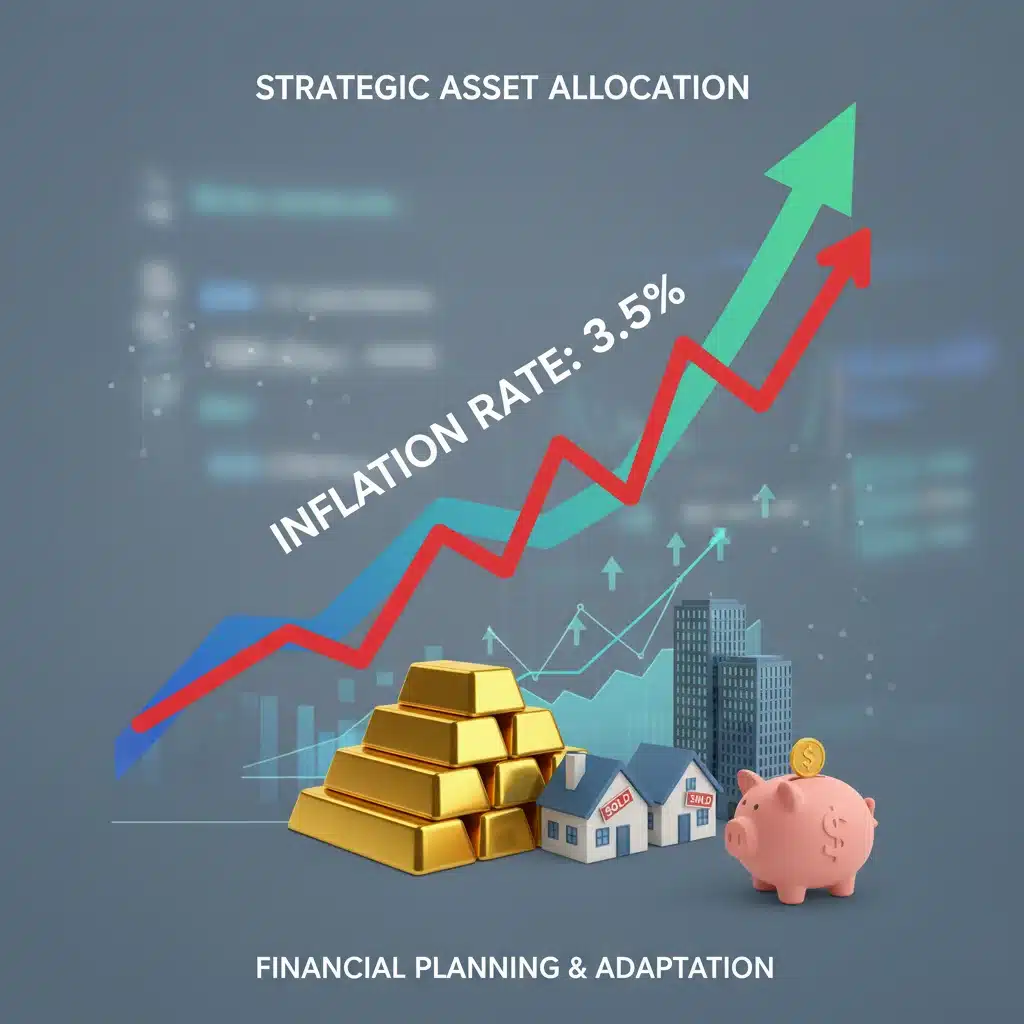
The economic landscape is perpetually shifting, and for investors, staying ahead of potential challenges is paramount. One such challenge looming on the horizon is the projected 3.5% inflation rate for 2026. While 3.5% might not sound alarming at first glance, its cumulative effect can significantly erode purchasing power and investment returns if not properly addressed. This comprehensive guide will delve into the intricacies of inflation, its potential impact on your wealth, and provide actionable strategies for making crucial inflation investment adjustments to your portfolio to safeguard and grow your assets.
Anúncios
Understanding Inflation and its Impact on Investments
Before we dive into specific inflation investment adjustments, it’s crucial to understand what inflation truly means for your money. Inflation is the rate at which the general level of prices for goods and services is rising, and consequently, the purchasing power of currency is falling. A 3.5% inflation rate means that something that costs $100 today will cost approximately $103.50 next year, and if this trend continues, the erosion of purchasing power becomes substantial over time.
The Silent Killer of Wealth
For investors, inflation acts as a ‘silent killer’ of wealth. It diminishes the real return on your investments. If your investments yield a nominal return of 5% but inflation is 3.5%, your real return is only 1.5%. In scenarios where inflation outpaces your nominal returns, you are effectively losing money in real terms. This is particularly concerning for fixed-income investments like traditional bonds or savings accounts, which often struggle to keep pace with rising prices.
Anúncios
Historical Context and Future Projections
Historically, periods of higher inflation have often been accompanied by shifts in market dynamics. The projected 3.5% for 2026, while not hyperinflationary, is higher than the Federal Reserve’s long-term target of 2%. This projection suggests that economic forces such as supply chain disruptions, increased consumer demand, or expansionary monetary policies could continue to exert upward pressure on prices. Understanding these underlying drivers is the first step in formulating effective inflation investment adjustments.
Assessing Your Current Portfolio’s Vulnerability to Inflation
The first step in making informed inflation investment adjustments is to assess how your existing portfolio is positioned to handle rising prices. Different asset classes react differently to inflation. Some are highly vulnerable, while others offer a degree of protection.
Fixed-Income Investments
Traditional fixed-income assets, such as government bonds, corporate bonds, and certificates of deposit (CDs), are generally highly vulnerable to inflation. Their fixed interest payments lose purchasing power as prices rise. If you hold a significant portion of your portfolio in these assets, their real returns will be significantly eroded by a 3.5% inflation rate.
Equities and Inflation
The relationship between equities and inflation is more nuanced. Certain sectors and companies can perform well during inflationary periods, especially those with strong pricing power that can pass on increased costs to consumers. However, companies with high operating leverage or those heavily reliant on specific commodities may struggle. Growth stocks, which derive much of their value from future earnings, can also be negatively impacted as higher inflation often leads to higher interest rates, which discount future earnings more heavily.
Real Estate and Commodities
Historically, real estate and commodities have been considered good inflation hedges. Real estate, particularly income-producing properties, often sees rents and property values increase with inflation. Commodities, such as oil, gold, and industrial metals, are raw materials whose prices often rise in an inflationary environment. However, these assets also come with their own risks and volatility.
Strategic Inflation Investment Adjustments for 2026
Now that we understand the impact of inflation, let’s explore specific strategies for making effective inflation investment adjustments to your portfolio. The goal is to build a portfolio that not only withstands inflationary pressures but potentially thrives in such an environment.
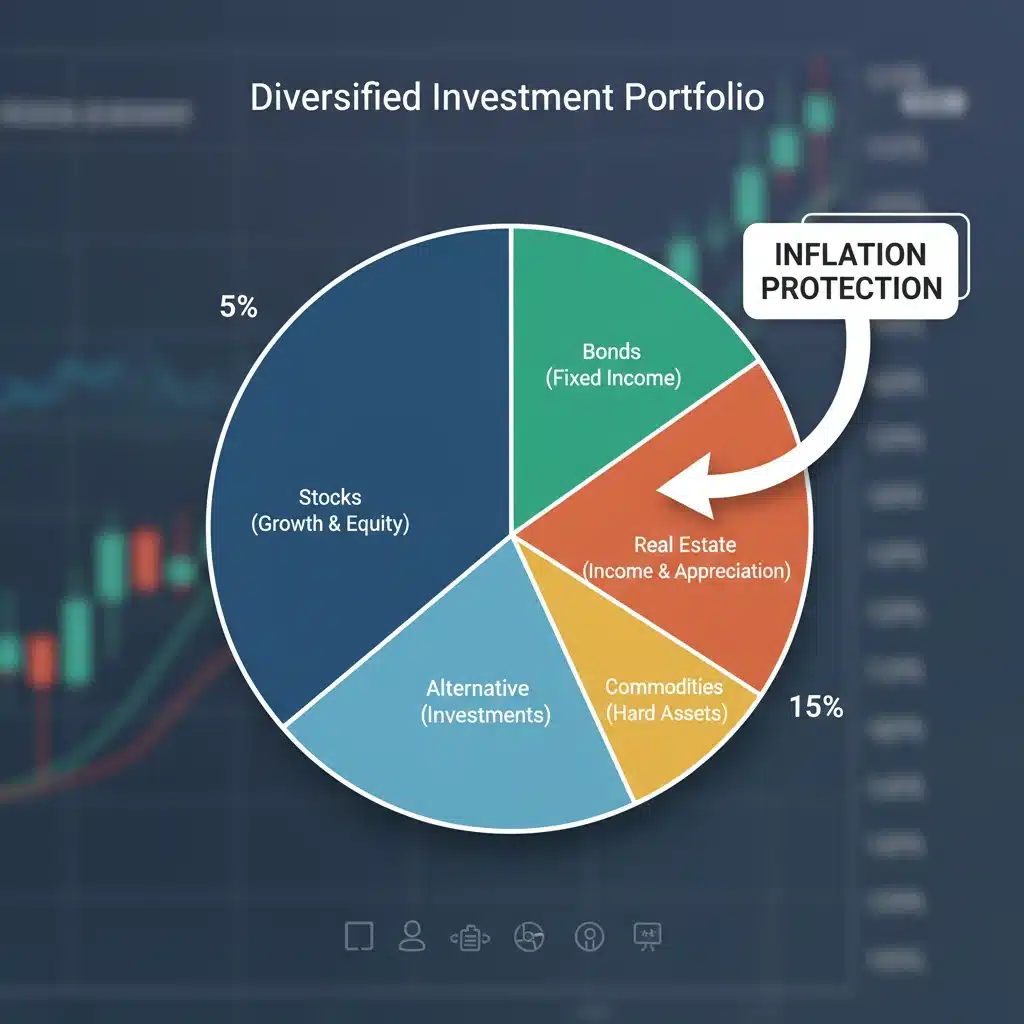
1. Diversify with Inflation-Protected Securities (TIPS)
Treasury Inflation-Protected Securities (TIPS) are bonds issued by the U.S. Treasury that are indexed to inflation. Their principal value adjusts with the Consumer Price Index (CPI), and interest payments are made on the adjusted principal. This means both your principal and interest payments increase with inflation, offering direct protection against rising prices. Including TIPS as part of your inflation investment adjustments can provide a reliable hedge against the erosion of purchasing power.
2. Consider Real Assets: Real Estate and REITs
Real estate has long been a favored asset during inflationary times. Property values and rental income tend to rise with inflation, providing a natural hedge. You can gain exposure to real estate directly by investing in physical properties or indirectly through Real Estate Investment Trusts (REITs). REITs are companies that own, operate, or finance income-producing real estate across a range of property sectors. They offer liquidity and diversification that direct property ownership might not. When making inflation investment adjustments, consider allocating a portion of your portfolio to REITs, especially those focused on essential services or high-demand sectors.
3. Allocate to Commodities
Commodities are raw materials used in the production of goods and services, such as oil, natural gas, precious metals (gold, silver), and agricultural products. Their prices often increase when inflation rises, making them effective inflation investment adjustments. You can invest in commodities through futures contracts, exchange-traded funds (ETFs) that track commodity indices, or by investing in companies that produce commodities. Gold, in particular, has historically been seen as a safe haven and a store of value during periods of economic uncertainty and inflation.
4. Focus on Companies with Pricing Power and Strong Balance Sheets
In an inflationary environment, not all companies are created equal. Businesses with strong pricing power – those that can raise prices without significantly impacting demand – are better positioned to maintain profit margins. Look for companies in essential sectors, those with strong brand loyalty, or those with unique products or services. Furthermore, companies with strong balance sheets, low debt, and consistent cash flow are more resilient to the challenges posed by rising costs and potential interest rate hikes. These types of equities can be valuable components of your inflation investment adjustments.
5. Evaluate Value Stocks Over Growth Stocks
While growth stocks have dominated markets for years, inflationary periods can sometimes favor value stocks. Value stocks are typically mature companies with stable earnings, strong fundamentals, and often pay dividends. When interest rates rise in response to inflation, the future earnings of growth companies are discounted more heavily, making their current valuations appear less attractive. Value stocks, with their more immediate earnings and dividends, can provide a more stable return profile during such times. Re-evaluating your allocation between growth and value is a prudent inflation investment adjustment.
6. Consider Floating-Rate Securities
Floating-rate notes (FRNs) and loans have interest rates that adjust periodically based on a benchmark rate, such as LIBOR or SOFR. This means that as interest rates rise in response to inflation, the income generated by these securities also increases, providing a hedge against rising prices. While they may carry more credit risk than government bonds, they can be a useful tool for managing interest rate risk within your fixed-income allocation as part of your inflation investment adjustments.
Advanced Strategies and Considerations for Inflation Investment Adjustments
Beyond the core asset classes, there are several advanced strategies and important considerations to keep in mind when making inflation investment adjustments.
Short-Duration Bonds
If you must hold bonds, consider short-duration bonds. These bonds are less sensitive to interest rate changes than long-duration bonds. While they may not offer the same inflation protection as TIPS, their lower interest rate sensitivity means their value will decline less if interest rates rise in response to inflation.
International Diversification
Inflation rates can vary significantly across different countries. Diversifying your portfolio internationally can help mitigate the impact of domestic inflation. Investing in countries with lower inflation rates or stronger currencies can provide a buffer. However, this also introduces currency risk and geopolitical risk, which need to be carefully considered.
Reviewing Your Debt Strategy
Inflation also impacts debt. For borrowers with fixed-rate debt, inflation can be beneficial as the real value of their debt decreases over time. However, for those with variable-rate debt, rising interest rates due to inflation can increase monthly payments. It’s crucial to review your personal debt strategy as part of your overall inflation investment adjustments. Consider consolidating variable-rate debt or refinancing to a fixed rate if appropriate.
Regular Portfolio Rebalancing
The economic environment is dynamic, and your portfolio should be too. Regular rebalancing is essential to ensure your asset allocation remains aligned with your risk tolerance and financial goals, especially when making inflation investment adjustments. This involves selling assets that have performed well and re-investing in underperforming assets to maintain your desired allocation. This disciplined approach prevents your portfolio from becoming over-exposed to certain risks or under-exposed to potential opportunities.
Consulting a Financial Advisor
Navigating inflationary periods can be complex, and individual circumstances vary greatly. A qualified financial advisor can help you assess your current portfolio, understand your risk tolerance, and develop a personalized strategy for making effective inflation investment adjustments. They can provide insights into specific investment vehicles and tax implications that are relevant to your situation.
The Psychology of Investing During Inflation
Beyond the technical aspects of inflation investment adjustments, it’s also important to address the psychological impact of inflation. Rising prices can create anxiety and lead to irrational investment decisions. Panic selling or chasing speculative assets are common pitfalls. Maintaining a long-term perspective and adhering to a well-thought-out investment plan are crucial.
Avoiding Emotional Decisions
Emotional responses to market fluctuations, especially during inflationary periods, can be detrimental to your financial health. Stick to your pre-defined investment strategies and avoid making impulsive decisions based on short-term news cycles or market rumors. Remember that inflation is a long-term phenomenon, and your investment strategy should reflect that.
Focusing on Real Returns
Shift your focus from nominal returns to real returns. This means always subtracting the inflation rate from your investment gains to understand your true purchasing power growth. This perspective helps you evaluate the effectiveness of your inflation investment adjustments and make necessary refinements.
Conclusion: Proactive Inflation Investment Adjustments for 2026
The projected 3.5% inflation rate for 2026 presents both challenges and opportunities for investors. By understanding the nature of inflation and its impact on various asset classes, you can take proactive steps to protect and grow your wealth. Implementing strategic inflation investment adjustments, such as diversifying into inflation-protected securities, real estate, commodities, and companies with strong pricing power, can significantly enhance your portfolio’s resilience.
Remember that a well-diversified portfolio, regular rebalancing, and a long-term perspective are your best allies in navigating an inflationary environment. While the future is uncertain, being prepared allows you to face economic shifts with confidence, ensuring your financial goals remain within reach. Don’t wait until inflation is a present threat; start making your inflation investment adjustments today to secure your financial future in 2026 and beyond.
Key Takeaways for Your Portfolio:
- Assess Vulnerability: Understand how your current assets react to inflation.
- Diversify Broadly: Incorporate TIPS, real estate (REITs), and commodities.
- Equity Selection: Favor companies with pricing power and strong financials; consider value stocks.
- Manage Debt: Review fixed vs. variable rate debt.
- Rebalance Regularly: Maintain your target asset allocation.
- Seek Professional Advice: A financial advisor can tailor strategies to your needs.